Higher fuel prices are putting pressure on airline earnings, sharpening the focus on which carriers can withstand a tougher operating environment. Financial resilience is central to the investment case for the sector.
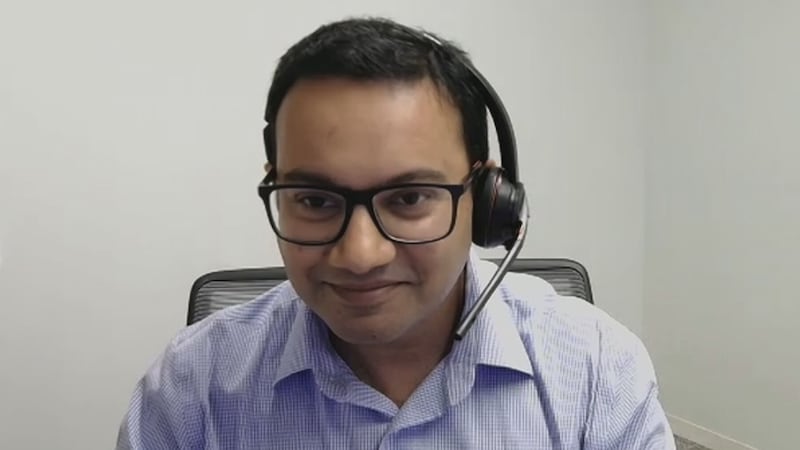
BNN Bloomberg spoke with Atul Maheswari, equity analyst at UBS, about why he favours Delta Air Lines, United Airlines and Southwest Airlines and how he assesses their prospects.
Key Takeaways
- Delta’s longstanding focus on premium travel has helped it maintain solid margins and cash flow through difficult operating conditions.
- Delta’s load factors increased year over year despite significantly higher fares, indicating continued passenger demand.
- United’s mix of premium seating, loyalty revenue, cargo and strong business travel helps it manage volatility.
- Southwest’s introduction of premium and assigned seating, alongside baggage policy changes, has helped lift its margins this year.
- Airline credit cards and loyalty programs generate higher-margin revenue than core flight operations while encouraging repeat business.
Read the full transcript below:
ANDREW: Our guest focuses on the airline sector and has three companies to put on your radar. Let’s bring in Atul Maheswari, equity analyst at UBS. Thank you very much indeed for joining us.
ATUL: Thank you for having me as well.
ANDREW: Start off with Delta, if you would. The company just warned investors about the impact of higher fuel prices, but you reckon the stock is attractive right now?
ATUL: I think so. And look, I mean, fuel is basically — it is what it is right now. But, you know, Delta has been one of the better-positioned airlines because of the premium exposure that they have. They’ve been on this premiumization journey for over a decade. That’s continuing to — that’s continuing to yield good results for Delta. And, you know, there is volatility right now with respect to earnings because of what fuel is doing. But really, if you look at how Delta has performed over the last few years, even in a tough operating environment, they’re still generating decent margins. They’re still generating a lot of cash flow, and the balance sheet is very strong. So, you know, on the other side of this, whenever fuel does moderate, we would expect this company to perform pretty well on both the top line as well as on the bottom line.
ANDREW: And so, you touch on this. They’re still loading up the planes even after increasing prices.
ATUL: They’re still loading up the planes. Their load factors, which is the percentage of planes that is — that is full, was up year over year, even in an environment wherein fares have moved up significantly. So that goes to show that, you know, consumers are still flying with Delta, even as, you know, fares have gone up.
ANDREW: United Airlines has a diversified stream of revenue, and that’s the reason you like the stock. Can you explain how do they have this big business mix?
ATUL: So, you know, both Delta and United, you know, with respect to the diversified business mix, they have a large portion of the business that’s coming from the front of the cabin, so the premium as well as the premium economy or the Premium Plus seating. Also, a good portion of revenues come from loyalty. There is also cargo in the mix, and in the case of Delta, there’s also MRO in the mix. So there’s this more widely diversified revenue base, as opposed to relying only on a single cabin and a single revenue stream. Another important business segment to keep in mind, in the case of United, but also for Delta, is that business travel’s a larger portion for both these enterprises, and business travel has been particularly strong. So having this diversified revenue mix helps them, you know, better manage business volatility during tougher times.
ANDREW: And Southwest Airlines, a model for so many discount airlines, what do you — what do you see that’s attractive here?
ATUL: I think what Southwest has done is something that’s remarkable. They have gone about taking that — to your point earlier, when you talk about them being a model for, you know, the budget or the low-cost enterprise airlines. They have successfully, over a short period of time, added premium seating. They’ve also changed various other elements of the business model, like going from open seating policy to, you know, more assigned seating. They’ve changed some policy around bags, around a bunch of different things to make them more attractive to what the consumers want and desire now versus, you know, how they used to look at flying in the past. So they’ve gone through all these changes in a very short period of time. Their execution has been excellent, and we’re also seeing the results of the changes that they have made in their — in their P&L. So their margins are up meaningfully this year. So clearly, these changes are benefiting Southwest. And also, in the case of Delta, United, even Southwest, these are only really the three airlines that are meaningfully profitable this year, even in this fuel backdrop, and they’ve got strong balance sheets. The key reasons why we like all three of them.
ANDREW: Before we let you go, I don’t know how new this is, but there’s a lot of investor attention being paid to the vast importance of credit cards for the airlines. Obviously, perks, etc., a way to attract customers. But airlines, for example, take in billions of dollars every year from the banks that run their credit cards. So the airlines are becoming more like banks.
ATUL: Yes, and look, I mean, these credit cards and, you know, the loyalty piece that I was talking about earlier, they provide a good medium for these airlines to attract customers that are loyal and that continue to want to fly with that particular airline to which they are loyal. We think the loyalty, the revenues that are generating — these cards or the overall loyalty program — are higher-margin revenues than, you know, the base business of running an airline. And this has become increasingly important in the U.S. because if you have, you know, a strong base of these loyalty customers, you’re able to get that repeat business. You’re able to get, you know, the higher-margin revenues, and it kind of builds, you know, a flywheel for these airlines in their respective margins. So this is increasingly important, and I see it becoming even more important in the future. And the top airlines that have these — the Delta, United, the Southwest — they are going to benefit more and more as we — as we’ll see this play out over the next few years.
ANDREW: Apparently, airlines are rushing to build ultra-luxe lounges around America to draw these credit card holders. I guess it’d be sitting on some anonymous bench in departures. Atul, thank you very much indeed for joining us.
ATUL: Thank you for having me as well.
ANDREW: Atul Maheswari, an equity analyst at UBS.
| DISCLOSURE | PERSONAL | FAMILY | PORTFOLIO/FUND |
|---|---|---|---|
| DAL:NYSE | N | N | Y |
| UAL:NASDAQ | N | N | Y |
| LUV:NYSE | N | N | N |
---
This BNN Bloomberg summary and transcript of the Oct. 14, 2026 interview with Atul Maheswari are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.