Low natural gas prices, consumer spending and demand for AI products are shaping how investors assess stocks across sectors. The discussion turns on what could sustain growth and justify current share prices.
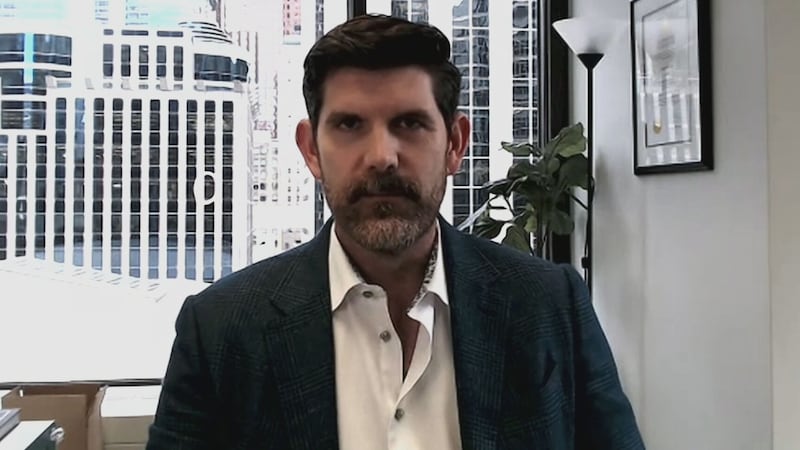
BNN Bloomberg spoke with Jamie Murray, president of The Murray Wealth Group, about opportunities and risks in energy, retail and technology.
Key Takeaways
- Murray says gas produced alongside oil and other liquids has added to supply and pressured natural gas prices.
- Greater access to LNG export markets could improve the prospects for Canadian gas producers, he says.
- Selling an asset to repurchase shares can appeal to a company when it considers its own stock undervalued.
- Membership growth and comments on consumer spending may offer more insight into a retailer’s earnings than sales figures already reported.
- Early interest in an AI assistant does not settle whether users will stay with it as competing products arrive.
Read the full transcript below:
ROGER: Tourmaline Oil is selling 50 per cent of its holdings in Topaz Energy and raising its quarterly dividend by five per cent. Let’s find out why. And joining me now to explain, Jamie Murray, president of The Murray Wealth Group. Jamie, thanks as always for joining us.
JAMIE: Thanks for having me on.
ROGER: Okay, I’ll just ask you that question. What’s—what are the plans Tourmaline has here?
JAMIE: Yes, I mean, clearly Tourmaline isn’t happy with the share price. I mean, it hasn’t really moved, you know, really from that $55 to $65 range all year long. We’ve seen a lot of other energy producers rallying, but, I mean, Tourmaline, the trouble they’re having is they’re overly leveraged to natural gas prices, particularly in Canada. I mean, they’ve worked to diversify, and they have, you know, some LNG contracts, and they sell into some other basins as well, where you get better pricing. But they really haven’t had the same leverage that we’ve seen from other producers. And so I think this is a management team that’s saying, “Hey, we have an asset that is trading at a fair value or even a premium value, and we can use that to buy our stock that we think is undervalued.”
ROGER: And was it the right amount? Should they move more? Should they move less?
JAMIE: So, I mean, I think it’s a pretty sizable stake they’re selling in Topaz. So, I mean, I think there’s a few considerations: you don’t want to flood the market with Topaz stock, you know. I mean, there still is a symbiotic relationship with Topaz because Topaz is really this—a lot of the midstream assets that Tourmaline used to own before they spun them out. So I think they probably do want to keep that corporate relationship there and that ownership relation. But, I mean, it’s a—it’s a decent chunk, and, I mean, would they do more if this continues or to help as the, you know, the gap widens even further? You know, I think I would say, why not?
ROGER: All right, they also raise their quarterly dividend. Is that worth noting, or is it just something that came in with this deal?
JAMIE: Yeah. So I think, you know, the management team of Tourmaline owns a lot of the company, so certainly this is a way for them to get some additional, you know, cash out of their investment, which, you know, it’s great that they own a lot, so not knocking that at all. But definitely, the dividend—they’re paying out a lot of their free cash flow, so it really depends on what happens with natural gas prices. But, you know, I think if they truly believe the stock’s undervalued, they’re going to want to continue these share buybacks, and you either dividend it out or you can buy back stock. And so I think it was a token dividend increase. You know, I think we’re going to need to see significantly higher natural gas prices to see the dividend grow at the historical rate that it has. So maybe more of a five per cent grower from here versus historically, I think, 10 to 20 per cent.
ROGER: And what are your thoughts on Tourmaline or Topaz interest? Do you own any?
JAMIE: So we’ve actually exited Tourmaline earlier this year. We owned it for a short period of time. We do, like I said, it’s a phenomenally run company. The problem is that being leveraged to natural gas, a commodity where, you know, other oil companies are drilling for liquids, natural gas is almost a byproduct of that production, and that’s just really crushed pricing, particularly in Canada, but in the United States as well. So, I mean, I think Tourmaline is a great play if we can open up Canada to export markets. And obviously, there are some new LNG facilities underway on the West Coast. But certainly, if we can accelerate that, get more LNG and more natural gas production moving out of Canada, that’s going to be when Tourmaline really takes off. So that’s what we’re looking to see to get more constructive on the name.
ROGER: Okay, I want to get your thoughts as well on Costco reporting its earnings after the bell today.
JAMIE: Yeah, so Costco, they report a monthly sales number every month, so their earnings are not quite the event that you might see for some other companies, given that the demand side is generally factored in. And then Costco has a very unique business model where they try and keep their gross margins in a pretty tight range. They like to pass savings on back to their members, and it’s really more about growing the membership base. So that’s always a number to look at: how the membership base is trending, how they’re handling the inflation that we’re seeing in the economy right now. So, you know, I don’t know if there’s going to be a huge move on this earnings coming out. Certainly, we’ve seen some other staples like Target do pretty well in their earnings. Walmart, you know, fell significantly, and they saw some weakness in some of their consumers, so it’s really going to be the commentary that we’re hearing on consumer spending that I think is going to be the most interesting thing from the quarter.
ROGER: Okay, I want to get to a couple of stocks you’re interested in. Meta has been on a nice little roll since Muse came out.
JAMIE: Yeah, I think it’s up another two or three per cent again today. So, certainly, investors are circling back to Meta now, as back into the AI winner pile. It seems like all these companies change who’s a winner, who’s a loser on a weekly or monthly basis, and it really comes down to whoever’s releasing, you know, the newest model. And if you can release a model or a product that catches on with consumers, which we can track through downloads and, you know, online feedback, that—that’s really what’s moving a lot of these AI stocks right now. And so Meta, they released their Muse AI assistant. It’s a—it’s a great product. I’ve tried it out. You can really use it to do anything you do on a website. So you can book a flight. You can order something on Amazon; it’ll make recommendations. Pretty interesting, but I think there’s a lot of excitement around this. But we’re going to see AI assistants from Google, from Chat, or, you know, OpenAI, Anthropic. So it’s going to be a very competitive space. But certainly, the market’s liking that Meta has an early lead in this, and that they built a product that is getting some consumer acceptance.
ROGER: Okay, we have to wrap it up there, Jamie. But thanks as always for joining us. Yeah, thanks a lot, Jamie Murray, president of The Murray Wealth Group.
---
This BNN Bloomberg summary and transcript of the Sept. 23, 2026 interview with Jamie Murray are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.