Concerns about technology companies’ spending on artificial intelligence are weighing on Nasdaq futures, despite an earnings beat from Taiwan Semiconductor Manufacturing Co. Gains elsewhere in equities point to a shift in trading sentiment.
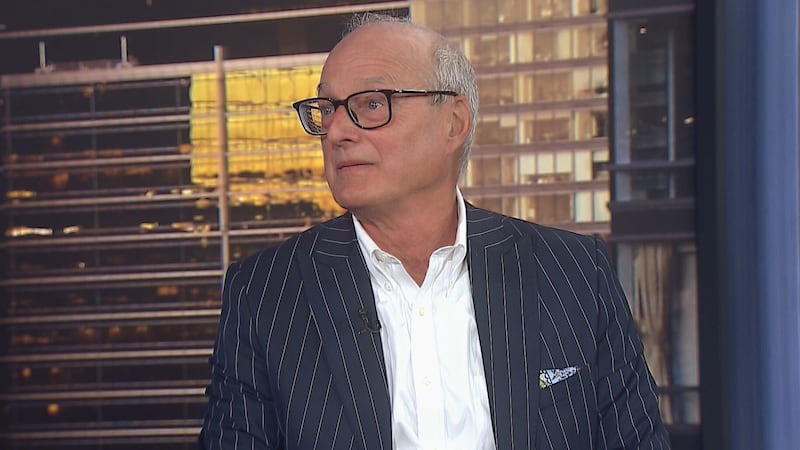
BNN Bloomberg spoke with Jim Thorne, chief market strategist at Wellington-Altus Private Wealth, about the AI spending debate, the latest U.S. economic data and his expectations for digital assets.
Key Takeaways
- Thorne says semiconductors have fallen about 15 per cent in October and describes the pullback as normal and healthy.
- He argues the AI buildout remains in its early stages, with robotics and agentic AI offering further growth potential.
- Thorne points to a below-consensus retail sales control-group reading as evidence of weaker underlying U.S. consumer spending.
- He expects U.S. bond yields to fall significantly, potentially supporting gains across banks, retailers and other sectors.
- Thorne sees tokenization, stablecoins and changes to U.S. legislation creating a major opportunity for digital assets.
Read the full transcript below:
ROGER: Well, concerns around tech companies overspending on AI are weighing on Nasdaq futures, despite an earnings beat from Taiwan Semiconductor, the largest contract chipmaker. Meanwhile, there are gains in areas outside of tech. Let’s get some perspective from Jim Thorne, chief market strategist at Wellington-Altus Private Wealth. Jim, thanks, as always, for coming in. Appreciate it.
JIM: Good morning. How are you?
ROGER: I saw you nodding your head on the — was it Bitcoin? Yeah. Was that what the nod was? And it’s going in the direction you’re expecting it to go.
JIM: You know, bearish-to-bullish reversal, market — significant market structure changes next year, and it’s akin to what happened in the early 2000s when China got accepted into the World Trade Organization. It’s not so much the asset; it’s the market structure around it which created a supercycle in, in commodities two decades ago. And we were, you know, a bunch of Canadians working in New York City, and there was no allocation to commodities. There was no sell-side support. There was no banking, and then we had this massive trade.
The exact same thing is going to happen with tokenization of assets, with stablecoins, with Ethereum, with Bitcoin. I would suggest nobody’s there. I would suggest when you look at a three to five per cent allocation, the Sharpe ratio of your portfolio goes up. There goes up. So we’re in that. In my views, we’re in the same type of playbook as when China got into the World Trade Organization, and all of these legislative changes are going to happen next year in the United States. So it’s a very interesting time.
ROGER: OK, that was a little sidebar there. You’re talking about Aaron. But I saw you nodding. I thought I’d ask your thoughts on it. What we’re seeing right now with the, with the AI sell-off, the tech sell-off, is that the start of something bad? Is that a little bit of a correction?
JIM: Stocks can have a 10 per cent correction. That’s normal, natural and healthy, and it’s great because you get all the short-term, you know, hot money out. The U.S., the SMH or the semiconductor industry, about down 15 per cent in October. It held in, in September and provided the ant — is that the counter-seasonal trade, so that the markets were up.
Look, I look at charts. The SMH can get back down to its 150-day moving average, upward-sloping, normal, natural and healthy. Look, I’m of the view that we are still in the early phases of this AI build; that we still haven’t gotten into robotics and agentic AI, and people are sitting there looking, using the old playbook and saying it’s over. Well, that’s where we are right now. We’re going to have people that disbelieve it. Got in early, but look, if you look at a company like Micron, Micron is booked out to ’28. Next year, they’re going to do $170 in earnings. It’s booked. It’s trading at six times forward. It’s trading at about 13 times trailing. Do 13 times 170, and then you just sit there and then ignore the noise.
So we’re still very early on, but yet this happens all the time. And when we do have it, investors have to understand that everybody’s going to come out: “It’s the end of the cycle. It’s the end of the trade. Get out.” That’s where we are right now.
ROGER: And what is driving that? What is driving that? Is it just — is it the capex spending? Is it — what has those concerns raised? I mean, I saw a stat that I think 20 per cent of companies have started to use agentic AI, and so that, that leaves another 80 per cent that could be looked.
JIM: Sure. I mean, we are. There’s no question that we’re in a historic AI capex cycle. One hundred per cent of tax — of capex is tax-deductible, tax-deductible in the United States when President Trump passed the big, beautiful bill. So the question is not that, is it a cycle or is it a bubble? Yes, that’s not profound. The question is, when does it end? I suggest you, Roger, it’s 2031, when the capex stops being 100 per cent tax-deductible. The bears out today are saying it’s going to happen next year, and if you listen to the companies, TSMC, you know, listen to Micron, what’s happening? They’re booked to ’28. So we’ve got two years of solid earnings in front of us. How the market discounts it? Well, that’s a different question.
ROGER: All right, want to get your thoughts on some other things that came out? Retail sales numbers out of the U.S. just came out a little better than expected, but not necessarily great.
JIM: No, because, as an economist, you sit there and look at what the control group says, and the control — headline was 0.8. Control is 0.1, which was below consensus. 0.1 feeds into the PCE and the, and the GDP numbers, so that was not a strong retail sales number.
But, Roger, the thing is, everybody now, because of AI and computers, we are investing off of headlines. Like yesterday, the CPI number, that was a weak CPI number. There were no second- and third-order effects. It was all driven by shelter. Shelter is an assumption, OK. And yet, at the same point in time, you say to people, if the Fed hikes rates, it makes shelter more expensive, which was the largest contributor to inflation. Why would you want the Fed to hike rates? And everybody goes, “Whoa, never thought of it that way.”
So that’s the type of — so, you know, when you see a headline number come in, for your viewers, stop, get the data, realize that the algos are going to trade off of the headlines, and then look at what’s going on, Roger. The 10-year right now is — yields are selling off in the United States. That’s the tell. I would suggest to you that we’ve got peak inflation, peak inflation fear, and yields are going to start to come down significantly.
And if that’s the case, what’s your portfolio look like? Going back to tech, tech was the only game in town. Maybe you want to buy banks here, right? Maybe you want to start thinking about the retailers. Maybe all those other areas. Maybe it broad — the market broadens out. Question.
ROGER: OK, got to wrap it up there, Jim. Always a pleasure when you come in. Thanks a lot. That was Jim Thorne, chief market strategist at Wellington-Altus Private Wealth.
---
This BNN Bloomberg summary and transcript of the Oct. 15, 2026 interview with Jim Thorne are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.