The Bank of Canada’s first interest rate increase in three years has put Canadian mortgage borrowing in focus. The decision raises questions about financing choices and housing affordability.
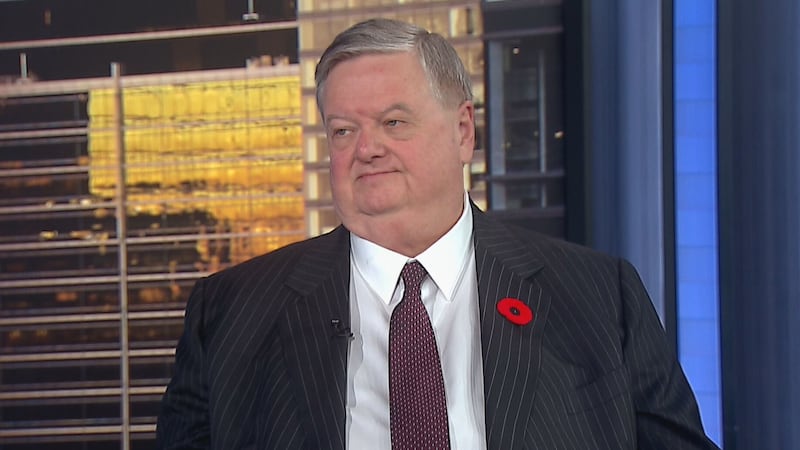
BNN Bloomberg spoke with Ron Butler, a mortgage broker at Butler Mortgage, about the implications for homeowners, prospective buyers and Canada’s housing sector.
Key Takeaways
- Mortgage rates approaching five per cent could prompt prospective buyers to delay purchases, Butler said.
- Falling home prices and rising borrowing costs can offset each other, although Butler favours securing a lower purchase price.
- Some variable-rate mortgage payments rise with interest rates. Others remain unchanged, with less of each payment going toward principal.
- Butler estimated an 80 per cent chance of another quarter-percentage-point rate increase at the Bank of Canada’s Dec. 9 announcement.
- Ontario and British Columbia face greater pressure because of their larger mortgages, Butler said. He also reported rising delinquencies in both provinces.
- Weak condo construction is adding to financial strain among construction workers and their families, according to Butler.
Read the full transcript below:
LINDSAY: The Bank of Canada raised interest rates this morning for the first time in three years. Joining us now to tell us what this means for Canadian mortgages is Ron Butler, a mortgage broker at Butler Mortgage. He joins us in the studio. It’s great to have you.
RON: Thanks for having me.
LINDSAY: How much of a damper do you expect this rate hike will put on the housing market?
RON: It’s got to have a major effect for this reason: We’ve had significant increases in fixed rates over the last two months, followed now by an increase in prime. Therefore, all variable-rate mortgages go up.
So, yes, it’s definitely a damper. I suspect we’re going to feel it right through into the new year.
LINDSAY: You previously warned that mortgage rates approaching five per cent could become a significant challenge for homebuyers. We’re moving closer to that five per cent level now. What’s important about that range?
RON: At that point, people really stop and think, “Maybe I should just wait. I see house prices are down in Ontario, down in British Columbia and coming down in some other provinces. But I don’t want to get into a bad mortgage rate situation. So I’ll just pause and keep watching.”
A pause is the toughest thing for a real estate market. People watching and waiting is very hard on the real estate market.
LINDSAY: How does that affect affordability?
RON: That is a total counterbalance. Prices come down, rates come up and you meet somewhere in the middle.
That being said, you’re always better off with the lower price. Rates move around. The price you locked in is the price you locked in.
LINDSAY: Tiff Macklem said in his opening remarks that additional rate hikes might be needed. You’re expecting one in December.
RON: Dec. 9, yes. The next announcement. I’d say there’s a strong 80 per cent chance we’re going to see another 25-basis-point increase.
LINDSAY: If we keep seeing that, even for one more increase, what does that mean for the housing market, homebuyers and prices?
RON: Everybody feels this in one way or another. Either your home equity line of credit rate went up, your payment went up or your personal line of credit rate went up.
With your variable-rate mortgage, at some banks and lenders, there is an increase in your payment. At some lenders, there isn’t. But even for those that are not increasing your payment, you’ve got less equity because you’re paying down less principal.
Everybody feels that. Everybody notices that. It is what the Bank of Canada governor intends it to be. It suppresses the Canadian economy.
LINDSAY: I wonder if you want to talk about that further. We were discussing it during the break, when you were talking about some lenders increasing payments and some not. In Canada, what are you seeing right now?
RON: Every lender will change its prime rate tomorrow, if not later today. So that will be in place.
Of the five biggest banks, four don’t change the payment. It takes multiple increases in the Canadian prime rate for them to change your payment. One does. You’ll see that change next month.
But when you’re trying to get a new mortgage, you’re coming to the bank and asking for a new mortgage, that’s a higher rate. It’s a higher rate on fixed. It’s a higher rate on variable. That means you’ve got less money to spend on anything else.
Your mortgage payment went up. You have less money for everything else at that point.
LINDSAY: What would you recommend right now: fixed or variable?
RON: I’m still a variable guy. Let’s say fixed is 4.69 per cent. After today, a good variable rate will be 3.75 or 3.8 per cent. It’s still less.
If it continues to go up, here’s the key: Someday it goes back down.
LINDSAY: In the meantime, it’s obviously been a struggle for some time. Have you been seeing that stress on mortgage holders so far, whether that’s missed payments, rising delinquencies or late payments?
RON: Delinquencies continue to rise in Ontario and British Columbia. There are indications that mortgage defaults are going to rise in the coming months. There are strong indications that there will be more foreclosures, power of sale proceedings and bank-ordered sales.
That just seems to be rising. It’s not huge. It doesn’t affect the banks, but it affects families, and it continues to affect families.
The worst thing is that you have less money to buy everything else when your mortgage goes up. When your initial mortgage goes up, you have to keep adjusting your budget at a difficult time. That’s the real impact.
LINDSAY: You mentioned Ontario and B.C., and I was going to ask you about that. As we discussed at the start, this is going to put a damper on the housing market, perhaps an additional damper.
Is it spread evenly across the board? Is it more Ontario and B.C.? Is it Vancouver and Toronto specifically? Where are you seeing the biggest impacts?
RON: It’s always Ontario and B.C. because we have the largest mortgages. We have the biggest house prices and the largest mortgages, so it’s more impactful there.
That said, Alberta prices have rolled over in the last nine months. Quebec prices have rolled over in the last five months. Everywhere you look in Canada, with the exception of Newfoundland and Saskatchewan, you’ve got impacts on the housing market that are not positive.
LINDSAY: What about houses versus condos? What differences are you seeing there?
RON: Right now, we’ve seen a bit of an upward movement in sales of brand-new townhomes in the Greater Toronto Area and other parts of Ontario. That’s because of the HST rebate.
That’s probably going to run out on April 1, and that’s going to be another bit of suppression.
As for condos, they just have problems. We’ve reached a point where they’re just not building any. Believe it or not—
LINDSAY: It doesn’t feel like it.
RON: They’re not building any. Believe it or not, just last month, only 156 brand-new condos were sold — condos to build. This used to be 10,000.
LINDSAY: It’s a saturated market, though, right?
RON: It is very much so. But this is an amazing drop in construction.
Interestingly, we’re starting to see more pain in construction workers’ families. We didn’t hear much of it last year, but we’re hearing more this year. The unemployment is continuing.
LINDSAY: The trickle-down effect is interesting to hear about as well. We’ve got to leave it there. We’re out of time.
Ron Butler, a mortgage broker at Butler Mortgage, we always appreciate you joining us. Thanks for coming in.
---
This BNN Bloomberg summary and transcript of the Oct. 28, 2026 interview with Ron Butler are published with the assistance of AI. Original research, interview questions and added context was created by BNN Bloomberg journalists. An editor also reviewed this material before it was published to ensure its accuracy and adherence with BNN Bloomberg editorial policies and standards.