The Productivity side of the AI trade is coming slowly. Those that are utilizing AI agents and tools already can see it. I believe that everyone with a computer or cell phone will have some degree of a paid monthly service for an AI assistant.
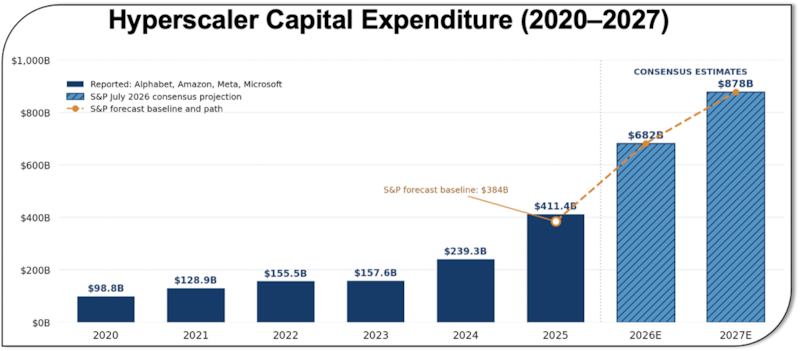
The CapEx required in the coming years alone to get there can boost GDP by enough to likely avoid a recession due a Federal fiscal cliff coming after the U.S. election. Odds are increasing that democrats take both houses of Congress according to the betting markets.
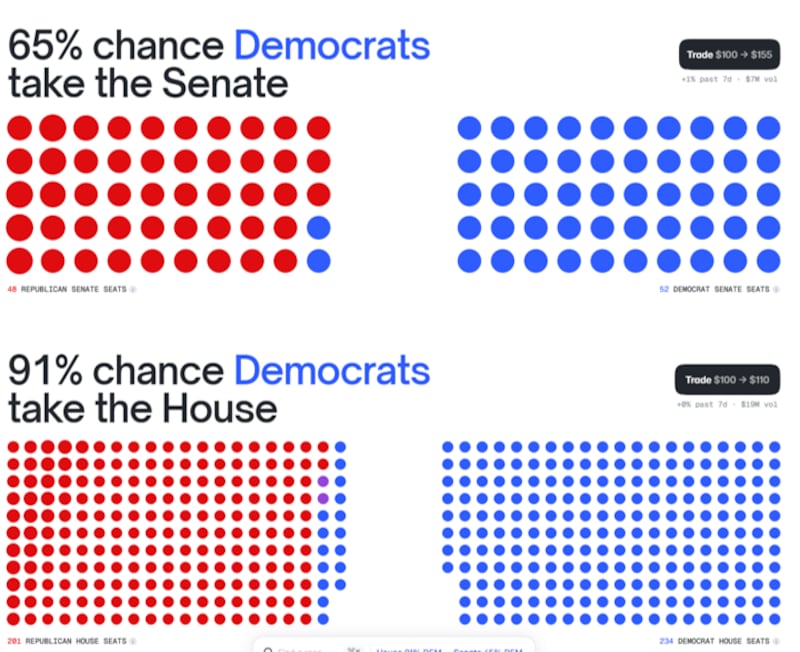
This opens the high possibility that Trump has a tantrum and shuts the government down blaming the Democrats. While the U.S. will not default on its debt, you can bet that will come up on social media posts and add another layer of uncertainty that U.S. hegemony is in decline.
Historically, markets like gridlock (Congress one party, White House opposite party). Less government manipulation has historically been a positive. Less spending out of Washington is good for at least one of the things the bond market was worried about and that is endless expanding deficits. While we can trust Washington and politicians in general to spend tax dollars with impunity, less pork is always seen as better.
Offsetting is still a massive spend to buildout the AI infrastructure, but several IPOs from data centre builders have been met with valuation concerns by investors.
In the next two weeks we hear from the hyperscalers (AMZN, META, MSFT, GOOGL etc...). If they start to change that forecast in the wrong direction, it could be the catalyst for some additional volatility that is already starting to surface (Coreweave).
The AI secondary supply chain, everything from semis, servers, transformers, electrical equipment, HVAC, steel, cement, aluminum, etc... that is flowing into creating and equipping these buildings.
The power and electrical grid contributions to reliably plug these buildings in has also benefited tremendously from the building. The forecast for energy needed is massive and measured over the next decade.
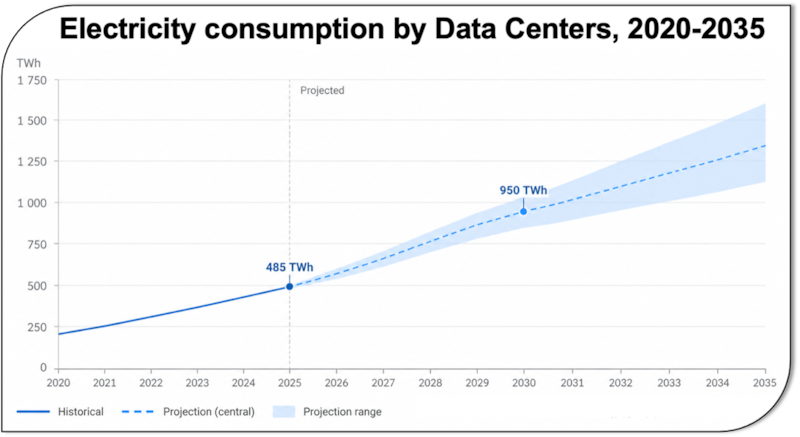
All these factors are inflationary now and driving economic growth. U.S. housing is in depression with 30-year mortgages and builder sentiment reports.
Outside of data centers, not much is happening in construction. These are the biggest variables when looking at GDP in an economy that is basically at full employment. The productivity gains are years away at scale, but something to look forward too.
I’m increasingly concerned that so much of the market cap of the world is concentrated in this generational transformation.
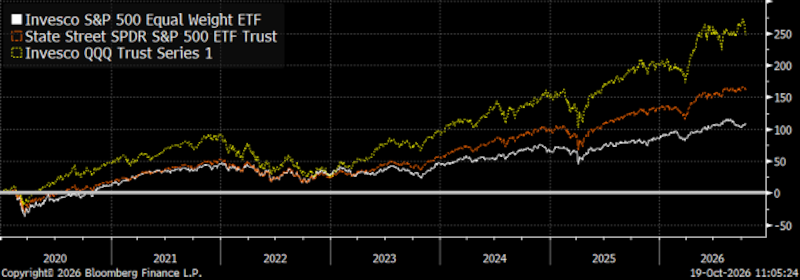
Looks to me that the equal weight S&P 500 offer much better value than the market cap weighted indexes.